

免职声明:本网站为公益性网站,部分信息来自网络,如果涉及贵网站的知识产权,请及时反馈,我们承诺第一时间删除!
This website is a public welfare website, part of the information from the Internet, if it involves the intellectual property rights of your website, please timely feedback, we promise to delete the first time.
电话Tel: 13002979178 OR 邮箱Email: Lngbbs@qq.com
摘要:环渤海动力煤价格指数报收于717元/吨 环比持平
|
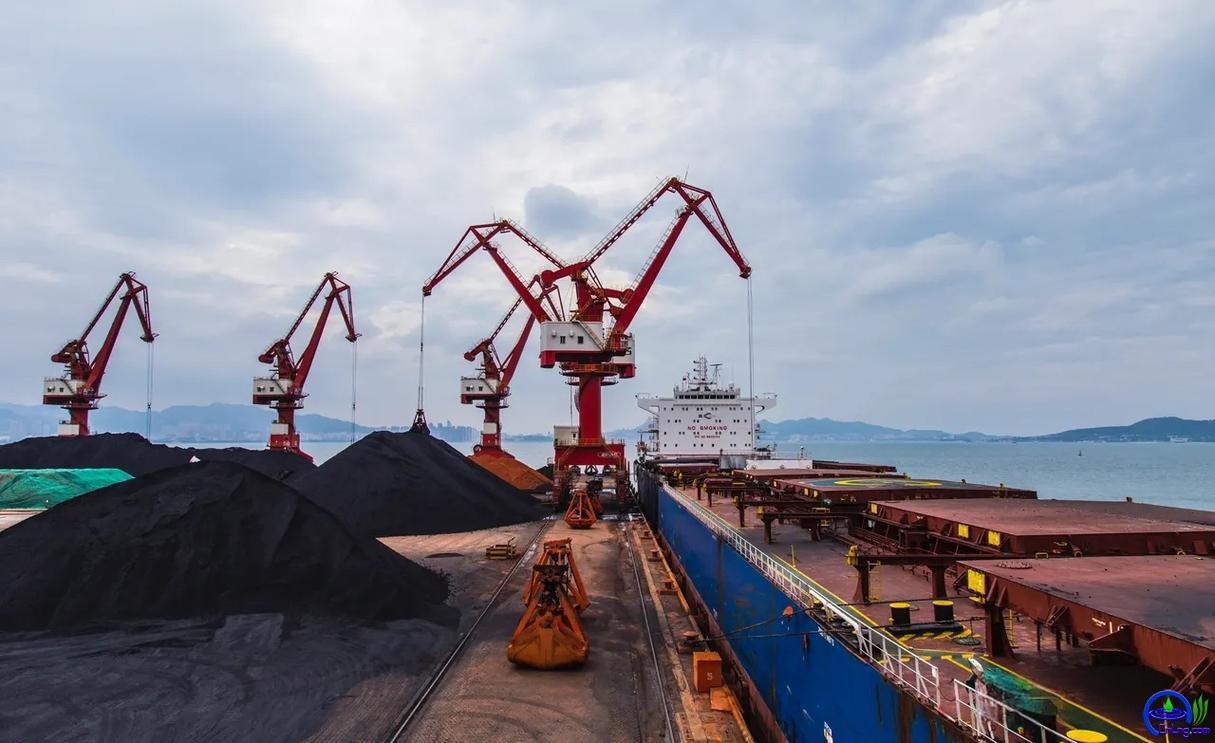
本报告期(2026年8月12日至2026年8月18日),环渤海动力煤价格指数报收于717元/吨,环比持平。 During this reporting period (from August 12, 2026 to August 18, 2026), the price index of thermal coal in the Bohai Rim region closed at 717 yuan per ton, remaining unchanged compared with the previous period. 从环渤海六个港口交易价格的采集情况看,本期共采集样本单位77家,样本数量317条。5500K热值(硫分:0.6%-1%)的现货综合价格为860元/吨,长协综合价格为701元/吨,现货与长协的计算比例为1:9。从计算结果看,本报告期,24个规格品价格全部持平。 Based on the collection of transaction prices from six ports along the Bohai Sea, a total of 77 sample units were collected this period, with a total of 317 samples. The spot market comprehensive price of 5500K calorific value (sulfur content: 0.6%-1%) was 860 yuan per ton, while the long-term contract comprehensive price was 701 yuan per ton. The calculation ratio between spot and long-term contract was 1:9. From the calculation results, it can be seen that the prices of all 24 specifications remained unchanged this reporting period. 盛夏步入尾声,沿海煤炭市场陷入现实与预期的双重博弈,市场交易主体避险观望情绪持续升温。多空因素交织作用下,沿海煤炭价格承压运行,本周期环渤海动力煤综合价格指数再度走稳。 As summer comes to an end, the coastal coal market is caught in a double game between reality and expectations. The sentiment of risk aversion among market participants continues to rise. Under the combined influence of various factors, the prices of coastal coal are under pressure and operate within a stable range. The comprehensive price index of coking coal in the Bohai Rim region has once again stabilized during this cycle. 一、供给约束强化,到港发运成本维持高位。7月份原煤产量同比降幅超一成,反映出前期煤矿复产进度不及预期,叠加近期各产区全面部署安监工作,主动检修、被动停产的煤炭企业数量增加,整体煤炭供应进一步趋紧,价格稳中有涨。下水货源备货不足、到港发运成本居高不下,仍给予部分港口卖方较强挺价支撑。 1. Supply constraints have intensified, and the cost of goods arriving at ports remains high. In July, the output of raw coal decreased by more than 10% year-on-year, indicating that the progress of coal mines resuming production was lower than expected. Coupled with the fact that all production areas have recently fully deployed safety supervision work and the number of coal enterprises conducting proactive maintenance and passive shutdowns has increased, the overall supply of coal has further tightened, and prices have remained stable with slight increases. The shortage of supplies for water transportation and the high cost of goods arriving at ports still provide strong support for sellers in some ports to maintain prices. 二、电煤消费区域分化显著,进口煤增量分流部分内贸煤需求。进入末伏,受“白海豚”残余环流东移影响,华东地区迎来大范围降雨,局部高温天气得到缓解,区域电厂耗煤自高位回落,降至历史同期最低水平,同比降幅7.7%,而华南地区高温高湿天气延续,电厂耗煤创历史同期新高,同比增幅达12.5%,电煤消费区域分化特征明显。 1. The consumption of thermal coal varies significantly by region, and the increase in imported coal has diverted some of the domestic demand. As the last period of summer approaches, due to the eastward movement of the remnants of the "White Dolphin" circulation, a large-scale rainfall has occurred in the East China region, alleviating the local high-temperature weather. The coal consumption of regional power plants has dropped from a high level and has fallen to the lowest level in history for the same period, with a year-on-year decrease of 7.7%. Meanwhile, the high-temperature and high-humidity weather persists in the South China region, and the coal consumption of power plants has reached a new high for the same period in history, with a year-on-year increase of 12.5%. The regional differentiation feature of thermal coal consumption is obvious. 华东地区作为内贸煤采购主力,耗煤量走低进一步加重市场观望情绪。与此同时,近期进口煤到岸量有所增加,尤其是澳煤履约兑现增幅明显,高热值煤市场需求得到一定补充,削弱了终端用户北上采购动能。 The East China region is the main buyer of domestic thermal coal. The decline in coal consumption has further intensified the market's wait-and-see sentiment. At the same time, the recent increase in the arrival of imported coal, especially the significant increase in the fulfillment of Australian coal contracts, has provided certain supplementation to the market demand for high calorific coal, weakening the purchasing momentum of end-users from the north. 三、运输周转效率持续偏低,环渤海港口开启累库进程。集港铁路运输疲软,即便部分路局降低铁路运费,仍难抵颓势。叠加多轮恶劣天气促使终端拉运节奏出现周期性变化,月中船舶稀少,环渤海港口空泊率走高。环渤海港口进出作业双低,库存转入累库阶段,买方市场属性进一步增强。 3. The transportation turnover efficiency remains persistently low, and the ports along the Bohai Sea have begun the process of inventory accumulation. The railway transportation for collecting goods is weak. Even though some railway bureaus have reduced railway freight charges, it still cannot reverse the trend. Coupled with multiple rounds of adverse weather conditions, the transportation rhythm at the terminals has undergone periodic changes. During the middle of the month, there were few ships, and the idle rate of ports along the Bohai Sea rose. The inbound and outbound operations at these ports were both low, and the inventory entered the stage of accumulation. The buyer's market attribute further strengthened. 综合来看,当前沿海煤炭市场呈现供需双弱格局,虽然供给侧有偏强支撑,但随着盛夏落幕,电煤消费即将步入传统季节性衰弱周期,市场对后市走势分歧将继续加大,多空博弈持续,短期价格继续承压。 Overall, the current coastal coal market is characterized by weak supply and demand. Although the supply side has some strong support, as summer comes to an end, the consumption of thermal coal for power generation is about to enter a traditional seasonal weakening cycle. Market opinions on the future trend will continue to diverge, with continuous supply and demand battles, and short-term prices will remain under pressure. 沿海航运市场方面,秦皇岛海运煤炭交易市场发布的海运煤炭运价指数(OCFI)显示,本报告期(2026年8月12日至2026年8月18日),沿海煤炭运价指数继续下行。截至2026年8月18日,运价指数报收1061.02点,与8月11日相比下行68.06点,降幅6.03%。 In the coastal shipping market, the Ocean Coal Freight Index (OCFI) released by Qinhuangdao Shipping Coal Trading Market shows that during this reporting period (from August 12, 2026 to August 18, 2026), the coastal coal freight index continued to decline. As of August 18, 2026, the freight index closed at 1061.02 points, down 68.06 points from August 11, representing a decrease of 6.03%. 具体到部分主要船型和航线,2026年8月18日与8月11日相比,秦皇岛至广州航线5-6万吨船舶的煤炭平均运价报54.5元/吨,环比下行3.2元/吨;秦皇岛至上海航线4-5万吨船舶的煤炭平均运价报41.5元/吨,环比下行5.3元/吨;秦皇岛至江阴航线4-5万吨船舶的煤炭平均运价报42.5元/吨,环比下行5.1元/吨。 Specifically for some major vessel types and routes, compared with August 11th, on August 18th, the average coal freight rate for 5-6万吨 vessels on the Qinhuangdao-Guangzhou route was reported at 54.5 yuan/ton, down by 3.2 yuan/ton compared with the previous day; the average coal freight rate for 4-5万吨 vessels on the Qinhuangdao-Shanghai route was reported at 41.5 yuan/ton, down by 5.3 yuan/ton compared with the previous day; and the average coal freight rate for 4-5万吨 vessels on the Qinhuangdao-Jiangyin route was reported at 42.5 yuan/ton, down by 5.1 yuan/ton compared with the previous day. |