

免职声明:本网站为公益性网站,部分信息来自网络,如果涉及贵网站的知识产权,请及时反馈,我们承诺第一时间删除!
This website is a public welfare website, part of the information from the Internet, if it involves the intellectual property rights of your website, please timely feedback, we promise to delete the first time.
电话Tel: 13002979178 OR 邮箱Email: Lngbbs@qq.com
摘要:动力煤假期多空博弈加剧,冬储驱动高位震荡
|
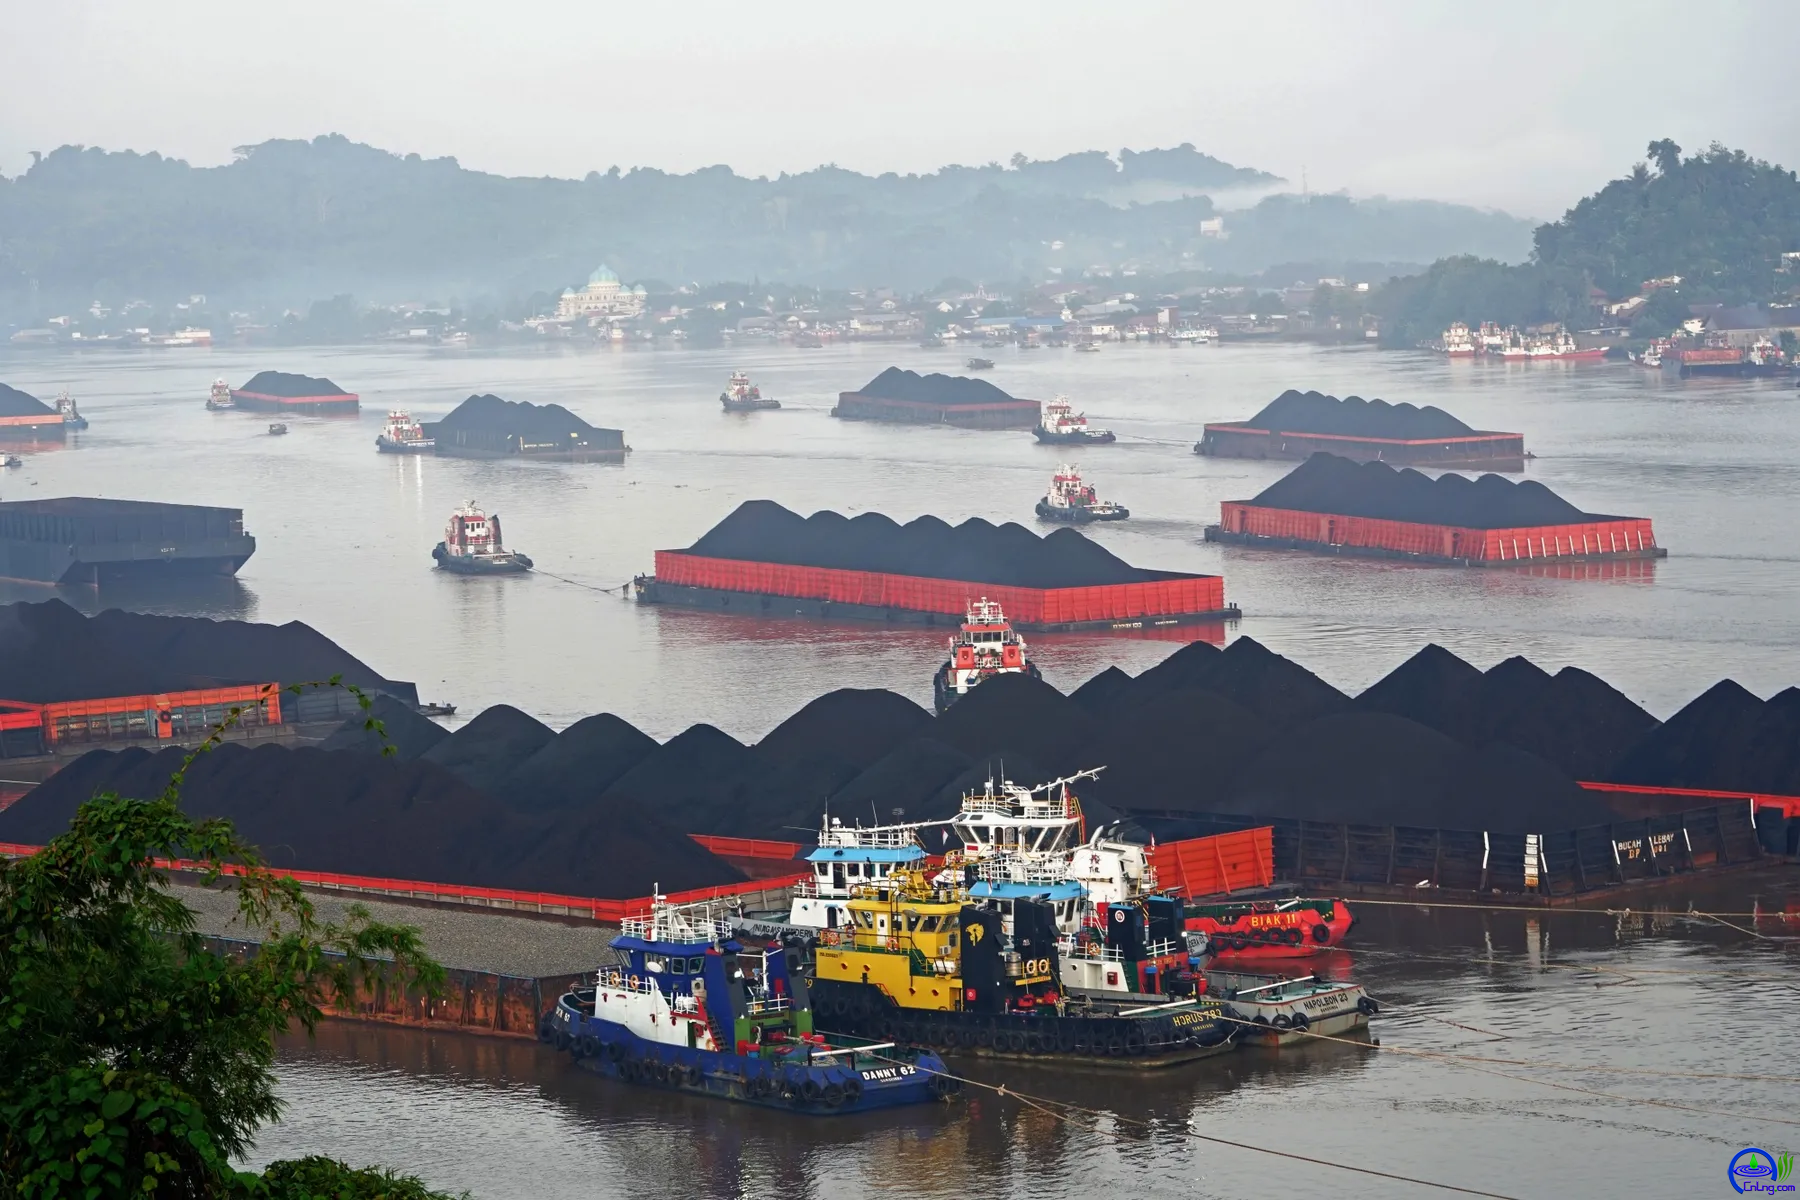
2026年国庆假期期间,国内外煤炭市场呈现明显的分化博弈格局,国内煤炭供需偏弱、价格结构性分化,港口市场低位挺价、产地涨跌分化显著,进口煤外盘坚挺但终端采购冷清;国际海运煤供给持续偏紧,海外需求稳步复苏,外盘价格维持高位。 During the National Day holiday in 2026, the domestic and international coal markets exhibited a distinct pattern of differentiation and competition. The domestic coal market showed weak supply and demand and a structural price divergence. The port market maintained a low-price stance while prices at production areas showed significant fluctuations. Imported coal saw a firm external market but the terminal purchases were sluggish. The supply of coal by international shipping remained tight, while overseas demand steadily recovered. The external market prices remained at a high level. 步入10月,煤炭市场正式进入秋冬切换关键节点,北方冬储补库周期开启、大秦线秋季检修落地,叠加国内稳产保供政策持续推进、海外煤炭贸易格局收紧,市场多空力量交织,煤价告别单边波动,正式进入高位震荡、结构性行情凸显的运行阶段。 Entering October, the coal market officially enters the critical transition period between autumn and winter. The winter storage replenishment cycle for the north has begun, the autumn maintenance work on the Dalian-Qinhuangdao Railway has been completed, coupled with the continuous implementation of domestic production stability and supply guarantee policies, as well as the tightening of overseas coal trade patterns, the market's supply and demand forces are intertwined. The coal price has bid farewell to single-directional fluctuations and officially entered a stage of high-level oscillation and prominent structural characteristics. 一、国庆假期市场整体复盘:多空博弈升温,结构性特征凸显 I. Market Review During National Day Holiday: Increased Battle Between Bulls and Bears, With Structural Characteristics Standing Out 国庆长假作为四季度煤炭市场的重要分水岭,彻底扭转了9月末的市场运行节奏,整体呈现“动力煤稳中有支撑、炼焦煤弱势承压,国内结构性分化、国际偏强坚挺”的格局。假期期间,国内终端企业多以消耗自有库存为主,市场集中补库动作缺席,交投整体清淡;供给端受主产区安监管控、铁路秋季检修筹备影响,增量释放有限,港口库存持续低位运行,为煤价筑牢底部支撑。 The National Day holiday served as a crucial turning point in the coal market during the fourth quarter, completely reversing the market operation rhythm at the end of September. The overall situation presented a pattern of "stable with support for thermal coal, weak and under pressure for coking coal, domestic structural differentiation, and international strong and firm". During the holiday period, domestic end-users mainly relied on consuming their own inventories, and there was a lack of concentrated market replenishment activities. Trading was generally sluggish. The supply side was affected by safety supervision in major production areas and preparations for autumn railway maintenance, resulting in limited increase in supply. Port inventories continued to operate at a low level, providing a bottom support for coal prices. 细分品类来看,动力煤市场多空博弈最为激烈,沫煤、普通原煤价格弱势回落,优质块煤、高卡稀缺资源货源紧缺、价格逆势坚挺;炼焦煤市场受下游钢焦行业需求疲软拖累,价格持续偏弱,竞拍流拍率偏高,市场支撑力度不足。国际市场方面,全球主流煤炭出口国供给持续收缩,印尼、澳洲、俄罗斯海运煤货源偏紧,外盘价格维持高位,对国内市场形成间接托底作用,但国内外价差及海运费上涨,压制了国内进口采购意愿,假期进口煤成交惨淡。整体而言,假期市场无系统性涨跌行情,结构性分化成为核心主线,也为10月整体行情定下高位震荡基调。 When looking at the market by category, the power coal market witnessed the most intense supply and demand competition. The prices of coking coal and ordinary raw coal declined weakly. High-quality lump coal and scarce resources with high calorific value were in short supply and their prices remained resilient against the trend. The coking coal market was affected by the sluggish demand from the downstream steel and coke industries, resulting in persistently weak prices and a high rate of failed auctions. The market's supporting force was insufficient. In the international market, the supply of major global coal exporters continued to shrink. The shipping coal supplies from Indonesia, Australia, and Russia were tight. The overseas prices remained high, providing an indirect support to the domestic market. However, the price gap between domestic and international markets and the increase in shipping costs dampened the willingness of domestic importers to purchase. The import coal transactions during the holiday were dismal. Overall, there was no systematic rise or fall in the market during the holiday. Structural differentiation became the core theme, and it set the tone of a high-level fluctuation for the overall market in October. 二、国内细分市场行情:动力煤结构分化,焦煤持续弱势 II. Domestic Market Segmentation Trends: The structure of thermal coal has become differentiated, while coking coal remains in a weak position. (一)动力煤:产地涨跌分化,港口低位挺价 (1) Thermal Coal: Producers show varying price movements, while ports maintain low prices with price support. 1.产地市场:品类分化显著,刚需支撑刚需价格。国庆假期国内陕蒙晋主产煤矿调价频次增多,市场呈现清晰的结构性涨跌格局。通用沫煤、原煤价格普遍回落,多数煤矿下调幅度集中在10-20元/吨,神木、府谷等区域部分原煤单品单日最大降幅达20元/吨,低端民用煤、普通原料煤货源充足,价格持续承压。与之相反,优质块煤、高卡动力煤资源稀缺,下游刚需采购韧性较强,价格逆势偏强运行,尔林兔、谊丰等矿区优质块煤报价维持高位,成为产地市场价格核心支撑。需求端来看,假期终端停工减产,电厂、化工企业无集中补库动作,坑口拉运仅维持刚需水平,整体成交节奏放缓,制约了产地煤价整体上行空间。 1. Origin Market: There is a significant differentiation in product categories, with the demand for necessities driving the prices of necessities. During the National Day holiday, the domestic coal mines in Shaanxi, Inner Mongolia and Shanxi provinces increased the frequency of price adjustments. The market showed a clear structural rise and fall pattern. The prices of general lump coal and raw coal generally declined, and most coal mines reduced the price by 10-20 yuan per ton. In some regions such as Shumusi and Fuyu, the maximum single-day price drop of some raw coal items reached 20 yuan per ton. There was an abundant supply of low-end civilian coal and ordinary raw coal, and their prices continued to be under pressure. On the contrary, high-quality lump coal and high-calorie thermal coal were scarce, and the downstream demand for necessities was relatively resilient. The prices of high-quality lump coal and high-calorie thermal coal in some mining areas remained at a high level, serving as the core support for the market prices at the origin. From the demand side, during the holiday, the terminals were shut down and production was reduced, and there were no concentrated replenishment actions by power plants and chemical enterprises. The transportation from the mining areas was only maintained at the level of necessities, and the overall transaction pace slowed down, restricting the overall upward space of the market prices at the origin. 2.港口市场:交投冷清,检修支撑底部稳固。假期北方港口暂停大规模交易,市场交投氛围清淡,价格保持平稳运行。截至10月7日,秦皇岛Q5500动力煤平仓价稳定在983-995元/吨,广州港同热值煤价维持1030-1050元/吨,南北港口价差保持稳定。库存端延续去化态势,环渤海港口整体库存回落至2400万吨以下,其中秦皇岛港场存610万吨、曹妃甸港1080万吨、京唐港523万吨,低位库存为煤价提供坚实支撑。核心利好来自运力端,10月7日大秦线正式启动为期20天的秋季集中检修,铁路运力收缩将大幅限制港口煤炭调入量,市场低价货盘稀缺,贸易商捂货挺价意愿强烈,但下游对高位煤价接受度有限,多按需小单采购,港口煤价上行动力不足,维持稳而不强的格局。 2. Port Market: Trading is sluggish, maintenance work supports the bottom and keeps it stable. During the holiday period, large-scale trading was suspended in northern ports, resulting in a quiet trading atmosphere in the market and stable prices. As of October 7th, the average settlement price of Q5500 thermal coal in Qinhuangdao remained at 983-995 yuan/ton, while the price of the same calorific value coal at Guangzhou Port remained at 1030-1050 yuan/ton. The price difference between the north and south ports remained stable. The inventory side continued to show a reduction trend, with the overall inventory of the Bohai Bay ports falling below 2400 million tons. Among them, the on-site inventory at Qinhuangdao Port was 610 million tons, Caofeidian Port was 1080 million tons, and Jingtang Port was 523 million tons. The low inventory provided a solid support for the coal price. The core positive factor comes from the transportation side. On October 7th, the Dacheng Line officially launched a 20-day autumn centralized maintenance. The contraction of railway transportation capacity will significantly limit the coal import volume into the ports, and there is a scarcity of low-price goods in the market. Traders have a strong desire to hold onto the goods and maintain the price. However, the downstream market's acceptance of high coal prices is limited, and they mostly purchase in small quantities according to their needs. The upward momentum of the port coal prices is insufficient, maintaining a stable but not strong situation. 3.终端需求:电厂库存充裕,日耗小幅回落。假期气温整体平稳,多地降温态势初显,但终端用电负荷环比回落。全国493家电厂日耗降至391.4万吨,环比减少16.6万吨,火电消耗力度有所减弱。目前电厂整体库存8839万吨,可用天数22.6天,库存处于合理偏高水平,终端暂无大规模补库压力,短期对煤价的需求支撑相对有限。 3. Terminal Demand: The power plant inventory is abundant, and the daily consumption has slightly decreased. The overall temperature during the holiday period was stable, and the cooling trend began to appear in many areas. However, the terminal electricity load has decreased compared with the previous period. The daily consumption of 493 power plants across the country dropped to 391.4 million tons, a decrease of 16.6 million tons compared with the previous period. The consumption of thermal power has weakened. Currently, the overall inventory of power plants is 883.9 million tons, with a usable days count of 22.6 days. The inventory is at a reasonable but elevated level. There is no large-scale replenishment pressure at the terminal level, and the short-term demand support for coal prices is relatively limited. (二)炼焦煤:供需偏弱持续,价格弱势运行 (2) Bituminous coal: Supply and demand remain weak, and prices continue to decline. 国庆假期炼焦煤市场延续弱势行情,整体呈现“供给缓慢修复、需求持续疲软”的格局。供给端,山西部分停产矿井逐步复产,但安全检查严格,整体复产进度偏慢,蒙煤通关量持续维持低位,国内炼焦煤供给增量有限,优质主焦煤货源仍偏紧。需求端压力凸显,下游钢铁行业盈利偏弱、铁水产量持续回落,钢厂对焦煤采购意愿低迷,多以消耗自有库存为主;焦炭首轮提降于10月1日正式落地,焦炭价格进入下行周期,压力向上游焦煤传导,进一步压制焦煤价格走势。 During the National Day holiday, the coking coal market continued to show a weak trend, presenting a pattern of "slow supply recovery and continued weak demand". On the supply side, some shut-down mines in Shanxi gradually resumed production, but the safety inspections were strict, and the overall resumption progress was slow. The customs clearance volume of Mongolian coal remained at a low level, and the supply increase of domestic coking coal was limited. High-quality main coking coal supplies remained tight. On the demand side, the pressure was prominent. The downstream steel industry had weak profits and iron water production continued to decline. Factories had low purchasing intentions for coking coal and mostly consumed their own inventories. The first round of price reduction for coke was officially implemented on October 1st. The price of coke entered a downward cycle, and the pressure was transmitted to the upstream coking coal, further suppressing the price trend of coking coal. 假期焦煤现货竞拍流拍率偏高,市场交投冷清,现货价格支撑持续弱化。不过盘面深贴水格局形成中长期估值支撑,且四季度部分煤矿完成年度生产任务后或主动减产,年内炼焦煤供给增量空间有限,预计10月中上旬焦煤将维持“弱势震荡、底部有支撑”的走势,大幅下跌空间受限。 The spot auction of coking coal during the holiday saw a high rate of failure. The market trading was sluggish, and the support for the spot price continued to weaken. However, the deep discount pattern formed on the market provides long-term valuation support. Moreover, some coal mines may voluntarily reduce production in the fourth quarter after completing their annual production targets. The supply increase of coking coal within the year is limited. It is expected that coking coal prices will maintain a "weak oscillation with support at the bottom" trend in the middle to upper part of October, and there will be limited room for a significant decline. 三、国际煤炭市场:外盘持续坚挺,全球供给格局偏紧 III. International Coal Market: Overseas markets remain strong, and the global supply situation is tight. 国庆假期国际海运煤炭市场延续偏强格局,全球供给收缩态势持续,海外需求稳步复苏,外盘价格高位坚挺。从核心出口国来看,印尼作为全球最大动力煤出口国,受RKAB配额审批滞后、内河干旱影响,矿区装船效率大幅受限,即期货盘供应紧张,支撑外盘价格走强,目前印尼3800大卡大船FOB报价稳定在79-81美元/吨。澳洲煤炭供给持续收缩,纽卡斯尔5500大卡动力煤FOB报价维持106-116美元/吨,价格韧性十足;俄罗斯远东港口动力煤价格虽小幅回落,但整体仍处于年内高位水平。 During the National Day holiday, the international maritime coal market maintained a relatively strong trend. The global supply contraction situation continued, while overseas demand steadily recovered. The prices on the foreign markets remained high and firm. From the perspective of major exporting countries, Indonesia, as the world's largest exporter of thermal coal, was affected by the delayed approval of the RKAB quota and the drought in the inland rivers, resulting in significant restrictions on the shipping efficiency of the mining areas. This led to a tight supply in the futures market, supporting the strengthening of the foreign market prices. Currently, the FOB price of 3800 kcal large vessels in Indonesia is stable at 79-81 US dollars per ton. The supply of Australian coal continued to shrink, and the FOB price of 5500 kcal thermal coal in Newcastle remained at 106-116 US dollars per ton, showing strong price resilience. Although the prices of thermal coal at the Russian Far East ports slightly declined, they remained at the high levels of the year. 需求端,欧洲地区气温回落、冬季取暖备货启动,火电需求稳步回升;印度、东南亚等新兴市场刚需进口稳定,全球煤炭贸易需求形成有力支撑。国内进口市场呈现“有价无市”格局,虽然进口煤与内贸煤仍存在小幅价差优势,但国庆期间国内采购商全面观望,叠加国际海运费走高抬升进口到岸成本,终端压价意愿强烈,市场仅零星小单成交,流标现象频发,进口煤短期难以拉动国内市场需求,仅对内贸煤价形成底部托底作用。整体来看,2026年以来印尼、澳洲、俄罗斯三大海运煤出口国持续收缩产能,全球海运煤供给格局偏紧,为四季度国际煤价提供长期支撑。 On the demand side, temperatures in Europe have dropped and preparations for winter heating have begun, leading to a steady increase in demand for thermal power generation. Coal demand in the European region has rebounded. In emerging markets such as India and Southeast Asia, stable demand for essential imports has been maintained, providing a strong support for global coal trade demand. The domestic import market has shown a pattern of "having value but no market". Although there is still a slight price advantage between imported coal and domestic coal, during the National Day holiday, domestic purchasers were all in a state of waiting and observing. Coupled with the increase in international shipping costs, the cost of imported coal at the port has risen, and the terminal's desire to negotiate lower prices is strong. Market transactions are only sporadic and small, and the phenomenon of no bids occurring frequently. In the short term, imported coal is unlikely to drive domestic market demand; it only has a bottom-pressing effect on domestic coal prices. Overall, since 2026, the three major maritime coal-exporting countries of Indonesia, Australia, and Russia have continuously reduced production capacity. The global supply pattern of maritime coal is tight, providing long-term support for international coal prices in the fourth quarter. 四、10月市场核心影响因素分析 IV. Analysis of Key Factors Affecting the Market in October (一)支撑因素:冬储需求+运力收缩+外盘托底 (1) Supporting factors: Winter storage demand + Capacity contraction + External market support 一是冬储补库需求逐步释放。10月北方地区正式进入秋冬取暖季,下游电厂、供暖企业将开启阶段性集中补库,刚需需求持续释放,将逐步带动煤炭日耗回升,为煤价提供核心需求支撑。二是铁路检修收缩运力。大秦线秋季检修落地,短期港口煤炭调入量受限,低位港口库存格局难以快速改善,贸易商挺价意愿持续强化,筑牢煤价底部。三是国际煤价高位托底。全球海运煤供给偏紧格局未改,外盘价格持续坚挺,进口煤成本居高不下,有效限制国内煤价下行空间。 First, the demand for winter storage and inventory replenishment is gradually being released. In October, the northern regions officially entered the autumn and winter heating season. Downstream power plants and heating enterprises will start to conduct phased centralized replenishment of inventory. The continuous release of necessary demand will gradually drive up the daily coal consumption, providing core demand support for coal prices. Second, railway maintenance reduces transportation capacity. The autumn maintenance of the Dacheng Line has been implemented, and the short-term import of coal at the ports is restricted. The low-level port inventory pattern is difficult to be rapidly improved. The willingness of traders to maintain prices has continued to strengthen, firmly stabilizing the bottom of coal prices. Third, international coal prices provide support at a high level. The global situation of tight supply of maritime coal has not changed. The prices on the foreign market have remained firm, and the cost of imported coal remains high, effectively limiting the downward space of domestic coal prices. (二)制约因素:保供发力+终端高库存+需求疲软 (2) Constraints: Supply-side efforts + High inventory at the terminals + Weak demand 一是稳产保供政策持续落地。国内持续推进煤矿安全稳产、停产矿井复产达产,煤炭供给边际修复预期升温,长期供给增量有望释放,压制煤价上行高度。二是终端库存相对充裕。目前电厂库存可用天数处于合理偏高水平,短期无集中补库刚需,难以形成持续需求拉动。三是工业需求分化偏弱。钢铁、建材行业传统淡季效应显现,工业耗煤需求回落,对冲化工、火电刚需增量,整体需求端缺乏超预期利好。 First, the policies for stable production and supply have continued to be implemented. Domestic efforts have been made to ensure stable production in coal mines and to resume production and reach full capacity in suspended mines, leading to an expectation of marginal improvement in coal supply. Long-term supply growth is expected to be released, which will restrain the upward trend of coal prices. Second, terminal inventories are relatively abundant. Currently, the available days of coal in power plants are at a reasonable and relatively high level. There is no urgent need for concentrated replenishment, and it is difficult to form sustained demand-driven growth. Third, industrial demand shows a relatively weak differentiation. The traditional off-season effects in the steel and building materials industries have become apparent, and industrial coal consumption demand has declined, offsetting the incremental demand from chemicals and thermal power. Overall, the demand side lacks unexpected positive factors. 五、10月中下旬市场行情展望 V. Market Outlook for Mid to Late October 综合供需、政策、运力及进出口格局来看,2026年10月国内煤炭市场将延续高位震荡、结构性分化的运行态势,整体涨跌幅度有限,多空博弈持续加剧,不同品类走势分化明显。 Taking into account supply and demand, policies, transportation capacity, and the import and export situation, the domestic coal market in China will continue to exhibit a state of high-level oscillation and structural differentiation in October 2026. The overall fluctuation range will be limited, and the competition between buyers and sellers will continue to intensify. The trends of different categories will show significant differentiation. 动力煤方面,短期将维持稳中有强、上行空间受限的格局。大秦线检修带来的运力收缩、港口低位库存及北方冬储补库需求,将持续支撑煤价底部;但电厂高库存、保供政策发力、下游高价承接乏力等因素,将限制煤价上涨空间。行情上,优质高卡煤、块煤货源偏紧,价格将偏强运行;普通沫煤、低卡原煤供给充足,价格弱势整理,结构性行情将持续演绎。 In terms of thermal coal, the market will remain in a stable but strong state with limited upward potential in the short term. The capacity reduction caused by the maintenance work on the Dalian-Qinhuangdao Railway Line, the low inventory at ports, and the demand for winter storage replenishment in the north, will continue to support the bottom of the coal price. However, factors such as high inventory in power plants, the implementation of supply guarantee policies, and the weak ability of downstream to absorb high prices will limit the upward potential of the coal price. In terms of the market trend, high-quality high-calorific coal and lump coal supplies will be tight, and their prices will run strongly; ordinary flake coal and low-calorific raw coal will have sufficient supply and will experience weak price consolidation, and a structural market trend will continue to play out. 炼焦煤方面,整体偏弱震荡基调难改。下游钢焦行业需求疲软的现状短期难以逆转,焦炭降价压力持续向上传导,压制焦煤价格走势;但供给端复产进度偏慢、优质资源紧缺,叠加盘面深贴水支撑,煤价大幅下跌空间封闭,预计10月中下旬焦煤将维持弱势震荡、底部逐步夯实的走势。 In terms of coking coal, the overall weak and fluctuating trend is unlikely to change. The current situation of weak demand in the downstream steel and coke industries is unlikely to be reversed in the short term. The downward pressure on coke prices continues to spread upward, suppressing the price trend of coking coal. However, the slow resumption of production in the supply side, the shortage of high-quality resources, and the deep discount in the market support have closed the space for a significant drop in coal prices. It is expected that coking coal will maintain a weak and fluctuating trend and gradually consolidate the bottom price in the middle and late October. 国际煤炭市场将持续高位坚挺,全球供给收缩格局延续,海外冬储需求稳步提升,外盘价格易涨难跌,持续为国内煤炭市场提供托底支撑。进口煤市场仍将以清淡成交为主,国内外价差及海运费波动将成为短期核心变量。 The international coal market will remain at a high and stable level. The global supply contraction pattern will continue. Overseas winter storage demand will steadily increase. The prices on the foreign market tend to rise rather than fall. They will continue to provide a bottoming support for the domestic coal market. The import coal market will still mainly feature sluggish transactions. The price difference between domestic and foreign markets and the fluctuation of shipping costs will become the core variables in the short term. 后续重点关注:一是大秦线秋季检修的运力收缩落地情况及港口库存变动;二是北方冬储补库节奏与电厂日耗回升幅度;三是主产区保供政策落地进度、煤矿复产增量及下游钢焦行业需求修复情况。 Subsequent key points of focus: First, the implementation status of the capacity reduction during the autumn maintenance on the Daqin Line and the changes in port inventories; second, the pace of winter storage replenishment in the north and the increase in power plant daily consumption; third, the progress of supply guarantee policies in major production areas, the increase in coal mine production, and the recovery of demand in the downstream steel and coke industries. |