

免职声明:本网站为公益性网站,部分信息来自网络,如果涉及贵网站的知识产权,请及时反馈,我们承诺第一时间删除!
This website is a public welfare website, part of the information from the Internet, if it involves the intellectual property rights of your website, please timely feedback, we promise to delete the first time.
电话Tel: 13002979178 OR 邮箱Email: Lngbbs@qq.com
摘要:煤电功能定位重塑 五大投资机遇显现
|
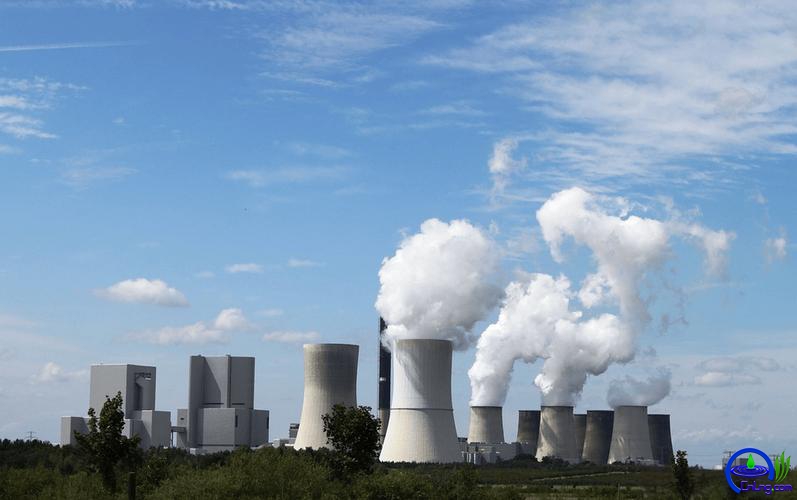
煤电低碳转型正成为“十五五”时期能源领域重要的系统性变革之一。在这场绿色浪潮中,煤电的功能定位正从“基础保障性电源”向“支撑调节性电源”发生根本性转变。 The low-carbon transformation of coal-fired power is becoming one of the significant systemic changes in the energy sector during the "14th Five-Year Plan" period. In this green wave, the functional positioning of coal-fired power is undergoing a fundamental shift from being a "basic guarantee power source" to a "supporting and regulating power source". 中国银河证券新发展研究院国际ESG研究中心主任、首席ESG分析师马宗明近日在接受中国证券报记者专访时表示,全球煤电转型路径呈现差异化,中国采取渐进式转型路线,将减排目标、电力系统安全保供和结构优化有机结合。在此过程中,煤电改造设备厂商、电网及电力设备厂商、煤电运营商、碳捕集利用与封存(CCUS)以及转型金融这五大方向蕴藏着重要的投资机遇。 Ma Zongming, the director of the International ESG Research Center of the New Development Institute of China Galaxy Securities and the chief ESG analyst, recently told a Chinese Securities Journal reporter in an exclusive interview that the global coal power transition paths are diverse. China has adopted a gradual transition approach, integrating emission reduction targets, power system security and supply guarantee, and structural optimization. During this process, there are significant investment opportunities in five major directions: coal power transformation equipment manufacturers, power grids and power equipment manufacturers, coal power operators, carbon capture, utilization and storage (CCUS), and transition finance. 全球煤电转型路线差异化明显 The global transition routes for coal power are significantly different from each other. 马宗明表示,全球煤电转型呈现差异化特征,各区域根据自身资源禀赋、经济发展阶段和政策目标选择了不同的转型路径和退出方式。从发电量看,传统化石能源仍是全球电力系统的基础电源,煤电占比整体缓慢下行。从装机容量看,随着风电和太阳能发电快速增长,清洁能源装机容量已几乎与化石能源相当。他认为,装机结构转型快于发电量结构,主要是因为风光出力受资源禀赋和天气波动影响,利用小时数低于煤电等传统电源。从在运和新增煤电厂分布看,全球煤电资产高度集中在亚洲,中国在运营煤电厂占全球总量的56.3%,是绝对主体。 Ma Zongming stated that the global coal power transition exhibits differentiated characteristics. Each region has chosen different transition paths and exit methods based on its own resource endowment, economic development stage, and policy goals. In terms of power generation volume, traditional fossil energy remains the basic power source of the global power system, and the proportion of coal power has been gradually declining overall. In terms of installed capacity, with the rapid growth of wind power and solar power generation, the installed capacity of clean energy has almost reached the level of fossil energy. He believes that the transformation of installed capacity structure is faster than that of power generation volume structure, mainly because the output of wind and solar power is affected by resource endowment and weather fluctuations, and the utilization hours are lower than those of traditional power sources such as coal power. From the distribution of operating and newly-built coal power plants, global coal power assets are highly concentrated in Asia. China's operating coal power plants account for 56.3% of the global total, making it the absolute dominant force. 从欧洲煤电领域看,马宗明表示,欧洲煤电退出进度较快,以强约束性气候政策推动可再生能源扩张。《欧洲气候法》明确2030年温室气体排放量较1990年至少下降55%,2050年实现碳中和。2026年至2030年是欧洲煤电机组退役高峰期,英国已于2024年9月关停最后一家煤电厂,成为G7中最先退出煤电的国家。 From the perspective of the European coal and electricity sector, Ma Zongming stated that the withdrawal of coal power in Europe has been progressing rapidly. Strongly restrictive climate policies have been used to promote the expansion of renewable energy. The "European Climate Law" clearly stipulates that greenhouse gas emissions should be reduced by at least 55% compared to 1990 levels by 2030 and achieve carbon neutrality by 2050. The peak period for the retirement of European coal power plants is from 2026 to 2030. The United Kingdom shut down its last coal power plant in September 2024, becoming the G7 country that exited coal power first. 对于美国市场,马宗明认为,美国煤电占比持续下行,天然气发电长期占据主导地位,但受制于反复摇摆的联邦政策,美国煤电退出仍具不确定性。 Regarding the US market, Ma Zongming believes that the proportion of coal power in the US continues to decline, while natural gas power generation has long held a dominant position. However, due to the inconsistent federal policies, the exit of coal power in the US remains uncertain. 马宗明表示,拉美地区可再生能源丰富,煤电占比较低,主要聚焦存量机组超低排放改造。而亚洲多数国家仍处于快速工业化和城镇化进程中,短期内难以退出煤电。 Ma Zongming stated that the Latin American region has abundant renewable energy resources and the proportion of coal power is relatively low. The focus is on the ultra-low emission renovation of existing power plants. However, most Asian countries are still in the process of rapid industrialization and urbanization, and it will be difficult for them to phase out coal power in the short term. 中国渐进式转型面临多重挑战 China's gradual transformation faces multiple challenges “我国既不简单效仿欧洲退出煤电,也不继续大规模扩张煤电资产,而要针对存量煤电资产进行灵活调峰功能改造和低碳化改造,差异化采取关停和延寿措施,少量新增高参数机组保障能源供应,以充足规模支撑能源安全,以高质量增量补齐系统调节能力短板。”马宗明在谈及我国的转型路径时表示。 "China neither simply follows Europe's model of phasing out coal power, nor continues to expand coal power assets on a large scale. Instead, it will carry out flexible peak-shaving function renovations and low-carbon renovations on existing coal power assets, adopt differentiated measures such as shutdowns and extensions, and add a small number of high-parameter units to ensure energy supply. This will be supported by a sufficient scale to ensure energy security, and with high-quality increments to make up for the shortcomings in system regulation capacity." Ma Zongming said when discussing China's transformation path. 马宗明认为,2025年是关键转折年,尽管煤电装机容量较2024年继续增长,但煤电发电量在多年连续增长后首次出现下滑,反映出电力结构优化进入新阶段。《新型能源体系建设“十五五”规划》要求到2030年风电和太阳能发电装机比重超过50%、非化石能源发电量比重达到50%,意味着煤电在新型电力系统中的功能定位将发生深刻重塑。 Ma Zongming believes that 2025 will be a crucial turning point. Although the installed capacity of coal-fired power plants continued to increase in 2025 compared to 2024, the power generation of coal-fired plants declined for the first time after years of consecutive growth, reflecting that the optimization of the power structure has entered a new stage. The "15th Five-Year Plan for the Construction of New Energy Systems" requires that by 2030, the installed capacity of wind power and solar power will exceed 50% and the proportion of non-fossil energy power generation will reach 50%, which implies that the functional positioning of coal-fired power in the new power system will undergo profound reshaping. 但煤电转型并非坦途,马宗明梳理了五大挑战:一是短期内灵活调峰与降碳矛盾突出,低负荷运行状态下机组效率降低、供电煤耗攀升,频繁启停增加碳排放。二是CCUS、生物质耦合发电、燃煤混氨掺烧等前沿低碳技术虽进入试点示范阶段,但成本高、运维难,短期内难以大范围推广。三是一半以上煤电机组于近15年内投产,设备较新且资产规模庞大,需警惕资产搁浅风险。四是煤电转型或对山西、内蒙古、陕西等煤炭资源型地区经济增长和就业存在潜在影响。五是煤电转型资金需求较大,但煤电机组的成本回收机制和转型金融支持体系尚不完善。 However, the transition from coal power to renewable energy is not an easy journey. Ma Zongming has identified five major challenges: Firstly, in the short term, there is a significant contradiction between flexible peak shaving and carbon reduction. During periods of low load operation, the efficiency of power generation units decreases, and the coal consumption for power generation rises. Frequent start-ups increase carbon emissions. Secondly, although cutting-edge low-carbon technologies such as CCUS, biomass-coupled power generation, and coal-fired mixed ammonia combustion have entered the pilot and demonstration stage, they are costly and difficult to maintain, and it is unlikely that they can be widely promoted in the short term. Thirdly, more than half of the coal power units were put into operation within the past 15 years. The equipment is relatively new and the asset scale is large, so the risk of asset obsolescence needs to be guarded against. Fourthly, the transition of coal power may have potential impacts on the economic growth and employment in coal resource-based regions such as Shanxi, Inner Mongolia, and Shaanxi. Fifthly, the transition of coal power requires a large amount of funds, but the cost recovery mechanism for coal power units and the financial support system for the transition are not yet complete. 针对上述挑战,马宗明建议构建覆盖市场机制、金融支持体系与区域治理的系统性支持框架。完善电力现货市场、中长期市场、容量市场和辅助服务市场机制,以反映煤电调峰价值,与碳市场联动疏导减排成本。将完善转型金融支持标准纳入对煤电关停和公正转型的支持。实施区域综合治理,设立就业保障与再培训体系,确保转型过程平稳有序。 In response to these challenges, Ma Zongming proposed to establish a comprehensive support framework covering market mechanisms, financial support systems and regional governance. Improve the mechanisms of the electricity spot market, medium- and long-term market, capacity market and ancillary service market to reflect the peak-load regulation value of coal-fired power and link them with the carbon market to guide the reduction of emissions costs. Incorporate the improvement of transition financial support standards into the support for the shutdown of coal-fired power and the fair transition. Implement regional comprehensive governance, establish an employment guarantee and re-training system to ensure a smooth and orderly transition process. 关注五大投资方向 Focus on the five major investment directions “煤电转型的挑战中同样蕴藏重大机遇。”马宗明认为,每一项尚未充分化解的风险,都对应着一个尚未被市场完全定价的投资机遇。 "The challenges of the coal-to-electricity transition also hold significant opportunities." Ma Zongming believes that every risk that has not been fully resolved corresponds to an investment opportunity that has not yet been fully priced by the market. 对于煤电改造设备厂商,马宗明认为这是最直接的受益主体。国内煤电低效产能存量仍具规模,亚临界机组占煤电装机总量的52.5%,30万千瓦及以下机组占比达43.7%。未实施改造的机组在低负荷调峰运行状态下效率明显下降,改造已成为刚性要求。马宗明判断,对照2027年升级改造目标及长期的低碳化、灵活调峰需求,这一领域市场空间广阔。 For manufacturers of coal power transformation equipment, Ma Zongming believes that they are the most direct beneficiaries. The domestic coal power's inefficient capacity still has a large scale. Subcritical units account for 52.5% of the total coal power installed capacity, and units with a capacity of 30,000 kilowatts and below account for 43.7%. The efficiency of untransformed units significantly decreases under low-load peak shaving operation conditions, and transformation has become a mandatory requirement. Ma Zongming judges that, in light of the 2027 upgrading and transformation targets and the long-term requirements for low-carbonization and flexible peak shaving, the market space in this field is vast. 谈及电网及电力设备厂商,马宗明表示,这一领域同样面临机遇。煤电转型与大规模新能源并网消纳相伴推进,储能与电网设备是不可或缺的核心支撑环节。随着风电、光伏渗透率持续提升,系统调峰、输电能力及储能配置需求同步增长。“煤电机组灵活性改造需与储能及电网升级协同发力。” When it comes to power grids and power equipment manufacturers, Ma Zongming stated that this sector also faces opportunities. The transition from coal-fired power to clean energy and the large-scale integration and absorption of new energy sources are advancing simultaneously. Energy storage and power grid equipment are indispensable core supporting links. As the penetration rates of wind power and photovoltaic power continue to increase, the demand for system peak regulation, transmission capacity and energy storage configuration is also growing simultaneously. "The flexibility transformation of coal-fired power units needs to be carried out in coordination with energy storage and power grid upgrades." 对于煤电运营商,马宗明表示,2025年煤电发电量首次下降,但调峰能力稀缺性凸显,资产价值反而得到提升。容量电价提升至能够覆盖固定成本50%以上,将显著改善煤电企业盈利水平,辅助服务市场扩容则打开了新的增长空间。在他看来,煤电机组改造占比较高的龙头运营商具备更大发展潜力。 For coal power operators, Ma Zongming stated that in 2025, the coal power generation volume will decline for the first time, but the scarcity of peak-load capacity becomes prominent, and the asset value actually increases. The capacity-based electricity price has been raised to cover more than 50% of the fixed costs, which will significantly improve the profit level of coal power enterprises and the expansion of the auxiliary service market will open up new growth space. In his opinion, the leading operators with a higher proportion of coal power plant renovations have greater development potential. 谈到CCUS,马宗明认为这是我国具备长期成长空间的重要赛道。他分析,至2060年,我国或将保留少量配套碳捕集设施的煤电机组用以中和残余碳排放。当前煤电已投运碳捕集项目总规模达235万吨,包含一座150万吨级运营项目、一座100万吨级在建项目以及一座400万吨级处于深化开发阶段的项目。马宗明表示,CCUS具备长期的降碳潜力,在碳中和场景下将应用于包括煤电在内的多个领域。随着技术持续突破与成本下行,行业有望释放广阔市场空间。 When it comes to CCUS, Ma Zongming believes that it is an important sector with long-term growth potential for our country. He analyzed that by 2060, our country may retain a small number of coal-fired power plants equipped with carbon capture facilities to neutralize residual carbon emissions. Currently, the total scale of carbon capture projects already in operation in the coal power sector amounts to 2.35 million tons, including a 1.5 million-ton operational project, a 1 million-ton construction project, and a 4 million-ton project in the deep development stage. Ma Zongming stated that CCUS has long-term potential for reducing carbon emissions and will be applied in multiple fields including coal power in the context of carbon neutrality. With continuous technological breakthroughs and cost reduction, the industry is expected to release a broad market space. 马宗明还表示,转型金融是煤电转型的核心支撑,本身也是重大投资机遇。脱碳改造、灵活性改造及前沿低碳技术等转型需求合计带动超10万亿元投资需求;国家级转型金融标准试点稳步推进,多个省份已出台地方标准;除转型专项贷款外,转型债券、火电ABS、火电基础设施REITs均已落地,具备规模化推广潜力。 Ma Zongming also stated that transformation finance is the core support for the coal and power industry transformation, and it is also a significant investment opportunity. The transformation demands such as decarbonization, flexibility improvement, and cutting-edge low-carbon technologies collectively drive investment demands of over 10 trillion yuan; the national-level transformation finance standard pilot is advancing steadily, and several provinces have already introduced local standards; apart from special loans for transformation, transformation bonds, power generation ABS, and power generation infrastructure REITs have all been implemented, and they have the potential for large-scale promotion. |