

免职声明:本网站为公益性网站,部分信息来自网络,如果涉及贵网站的知识产权,请及时反馈,我们承诺第一时间删除!
This website is a public welfare website, part of the information from the Internet, if it involves the intellectual property rights of your website, please timely feedback, we promise to delete the first time.
电话Tel: 13002979178 OR 邮箱Email: Lngbbs@qq.com
摘要:中国进口动力煤市场僵持,电厂需求转向9月船期
|
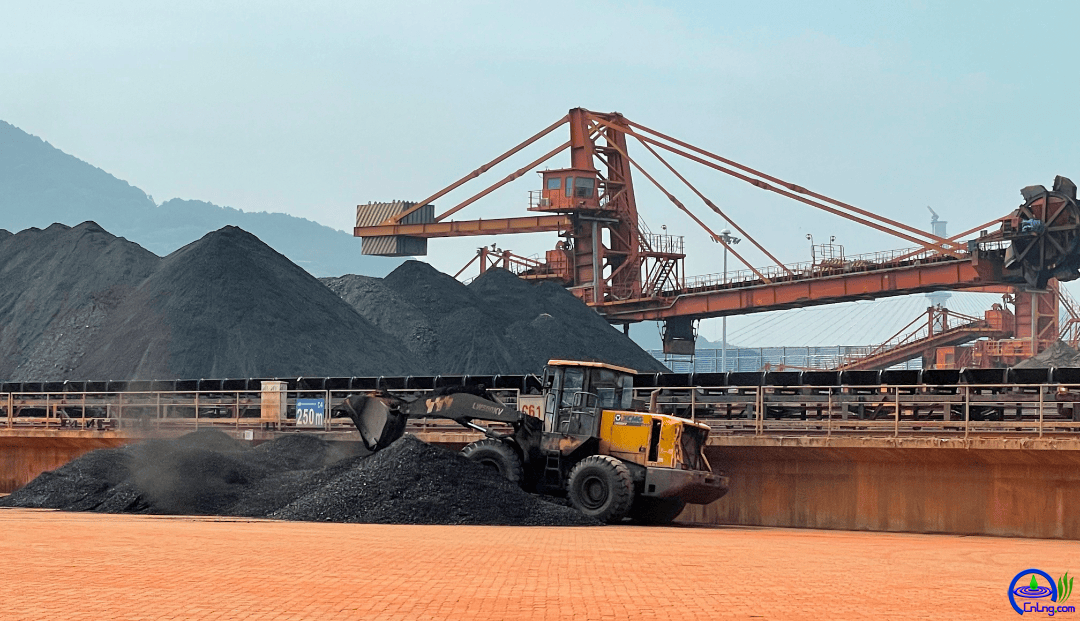
7月29日,中国海运进口动力煤市场延续疲态,电厂招标价格小幅走低。贸易商为消化库存竞相压价,而强降雨短期压制南方沿海电厂煤耗,需求端最新招标关注点已转向淡季交货船货。 On July 29th, the Chinese maritime import market for thermal coal continued its sluggish trend, with the bidding prices of power plants showing a slight decline. Traders were competing to lower prices in an effort to clear their inventories, while heavy rainfall temporarily reduced the coal consumption of power plants in the southern coastal areas. The latest focus of demand-side bidding has shifted to off-season shipping cargo. 近日华能集团发布招标,采购13船海运进口动力煤(热值3000-5500大卡),总量高达83.6万吨,其中75%要求9月交货。 Recently, the Huaneng Group issued a tender to purchase 13 ships of imported thermal coal by sea (with calorific values ranging from 3,000 to 5,500 kcal). The total quantity amounts to 836,000 tons, and 75% of the orders require delivery by September. 贸易人士对后市看法偏谨慎。电厂8月货源基本落定,现正寻购9月船货,而9月通常为需求淡季,部分机组计划检修,煤炭消耗趋缓。 Trade experts are cautiously optimistic about the future. The supply for power plants in August has basically been secured. Currently, they are looking to purchase shipping cargo for September. September is usually a slack demand period, and some power plants plan for maintenance, resulting in a slowdown in coal consumption. 与此同时,整体市场仍陷胶着。海外报价基本平稳,但国内采购兴趣不足,试探性报盘偏低。 Meanwhile, the overall market remains in a stalemate. Overseas quotations remain relatively stable, but domestic purchasing interest is lacking, and tentative offers are relatively low. 消息人士称,虽有招标进行,但电厂实际采购仍有限,部分电厂据闻流标,给投标价带来下行压力。一位华南贸易商补充称,虽报价难以吸引电厂采购,但鉴于海外报价坚挺,贸易商不愿进一步降价,市场陷入僵持。 Sources said that although there were tenders conducted, the actual purchasing by power plants remained limited. Some power plants were reportedly unsuccessful in their bids, putting downward pressure on the bidding prices. A trading source from South China added that although the quotations were not attractive to power plants for purchase, given the strong overseas quotations, traders were reluctant to further reduce prices, and the market was in a stalemate. 当日,南方某电厂9月下旬交货的印尼3800大卡动力煤投标价低至549元/吨(华南到岸含税价),折合巴拿马型船离岸价约62.7美元/吨。这仍远低于海外矿商65美元/吨左右的离岸报价。南加里曼丹至华南的巴拿马型船运费在8.7-9美元/吨之间,且继续受到国际原油价格影响。 On that day, the bidding price for the Indonesian 3800 kcal thermal coal delivered by a power plant in the south in late September was as low as 549 yuan per ton (including tax at the destination in South China), which was approximately 62.7 US dollars per ton on the Panamax ship's free port price. This was still far lower than the free port price of around 65 US dollars per ton quoted by overseas miners. The Panamax ship's freight from South Kalimantan to South China was between 8.7 and 9 US dollars per ton, and it continued to be affected by international crude oil prices. “进口煤价与国内投标价仍倒挂,价差估计在20元/吨左右,贸易商难以盈利参与。”第二位贸易商表示。“更偏空的是,南方主要港口库存相对偏高,加上电厂库存充裕,电厂整体采购意愿不强。” "The price of imported coal still lags behind the domestic bidding price, with the price difference estimated to be around 20 yuan per ton. Traders find it difficult to make a profit and participate in the trade." said the second trader. "What's more bearish is that the inventory at major ports in the south is relatively high, and with abundant inventory at power plants, the overall purchasing intention of power plants is not strong." 中国煤炭资源网数据显示,截至7月28日,广州港存煤341万吨,月环比上升4%,同比上升13.9%。截至7月24日,防城港存煤达383万吨,为2025年3月中旬以来最高。 Data from China Coal Resources Network shows that as of July 28th, the coal stock at Guangzhou Port was 3.41 million tons, up 4% month-on-month and 13.9% year-on-year. As of July 24th, the coal stock at Fangchenggang Port reached 3.83 million tons, the highest since mid-March 2025. 台风季华南地区持续降雨进一步打压市场情绪,拖累沿海电力和煤炭消耗。台风“诺尔”残余深入内陆,气象部门警告称,减弱后的风暴在内陆停留时间可能比往常更长,威胁南方和中部大片地区引发严重洪灾。中央气象台预计,南方部分省份强降雨将持续至7月底。 The continuous rainfall in the South China region during the typhoon season further dampened market sentiment, dragging down the consumption of electricity and coal along the coast. The remnants of Typhoon "Noel" have advanced inland, and the meteorological department warns that the weakened storm may stay in the inland areas for a longer period than usual, threatening to cause severe floods in large areas of the south and central regions. The Central Meteorological Observatory predicts that heavy rainfall in some southern provinces will continue until the end of July. 供应方面,印尼矿商对增产仍持谨慎态度,因RKAB采矿配额审批存在不确定性。多数市场参与者预计配额审批将在8月中旬完成,届时矿商可能增产,但主要生产商目前增产意愿不强。 On the supply side, Indonesian miners remain cautious about increasing production due to the uncertainty surrounding the approval of mining quotas by RKAB. Most market participants expect the quota approval process to be completed by mid-August, at which point miners may increase production. However, major producers currently lack a strong desire to increase production. 高卡煤方面,澳洲5500大卡动力煤报价在离岸价96美元/吨左右,实际成交听闻在离岸价94美元/吨。澳洲至华南的好望角型船运费约17.7-18美元/吨,与巴拿马型船运费18-19美元/吨的价差收窄。 Regarding high-calorie coal, the quoted price of 5500 kcal thermal coal in Australia is around 96 US dollars per ton FOB, and the actual transaction price is heard to be 94 US dollars per ton FOB. The freight cost from Australia to South China via Capesize ships is approximately 17.7 - 18 US dollars per ton, and the price gap with Panamax ships' freight of 18 - 19 US dollars per ton has narrowed. 尽管成交清淡,但多数贸易商仍认为下行空间有限,因海外价格坚挺且印尼供应存在不确定性。部分人士预计,一旦天气模式转变且港口库存持续下降,市场方向将更加明朗,部分参与者也在关注中国国内市场信号。 Although trading volumes were low, most traders still believe that the downward space is limited, as overseas prices remain firm and there is uncertainty regarding supply from Indonesia. Some people predict that once the weather pattern changes and port inventories continue to decline, the market direction will become clearer. Some participants are also paying attention to signals from the Chinese domestic market. 北方港低卡煤供应偏紧支撑价格 The shortage of low-calorie coal supply in the northern port supports the price. 中国北方港口动力煤市场仍陷僵持,但低卡煤结构性短缺仍对价格构成支撑,在一定程度上抵消了电厂高库存及短期台风抑制耗煤带来的需求疲软。 The power coal market in northern China's ports remains in a stalemate, but the structural shortage of low-calorie coal still supports prices, to some extent offsetting the weak demand caused by high coal inventories in power plants and the short-term impact of typhoons on coal consumption. 消息人士称,环渤海主要港口4500大卡动力煤日益稀缺,部分报价坚挺至645-650元/吨(离岸含税价),较周初的640元/吨上涨。供应偏紧主要归因于山西省持续的安全检查,部分煤矿停产或减产,区域供给收缩,部分需求外溢至其他产区。 Sources indicate that 4500 kcal thermal coal at major ports along the Bohai Sea is becoming increasingly scarce. Some quotations have remained firm at 645-650 yuan/ton (including tax and cost for overseas delivery), up from 640 yuan/ton at the beginning of the week. The supply shortage is mainly attributed to the continuous safety inspections in Shanxi Province, with some coal mines shutting down or reducing production. Regional supply has contracted, and some of the demand has spilled over to other production areas. 港口库存持续下降,部分因船舶周转恢复,给市场带来一定利好支撑。截至7月29日,秦皇岛港、曹妃甸港和京唐港合计存煤2623万吨,为连续第九日下降,较7月20日的近期高点下降7.5%。 Port inventories have continued to decline, partly due to the recovery of vessel turnover, providing some positive support for the market. As of July 29th, the combined coal stockpile at Qinhuangdao Port, Caofeidian Port and Jingtang Port stood at 26.23 million tons, marking the ninth consecutive decline and a decrease of 7.5% from the recent peak on July 20th. |