

免职声明:本网站为公益性网站,部分信息来自网络,如果涉及贵网站的知识产权,请及时反馈,我们承诺第一时间删除!
This website is a public welfare website, part of the information from the Internet, if it involves the intellectual property rights of your website, please timely feedback, we promise to delete the first time.
电话Tel: 13002979178 OR 邮箱Email: Lngbbs@qq.com
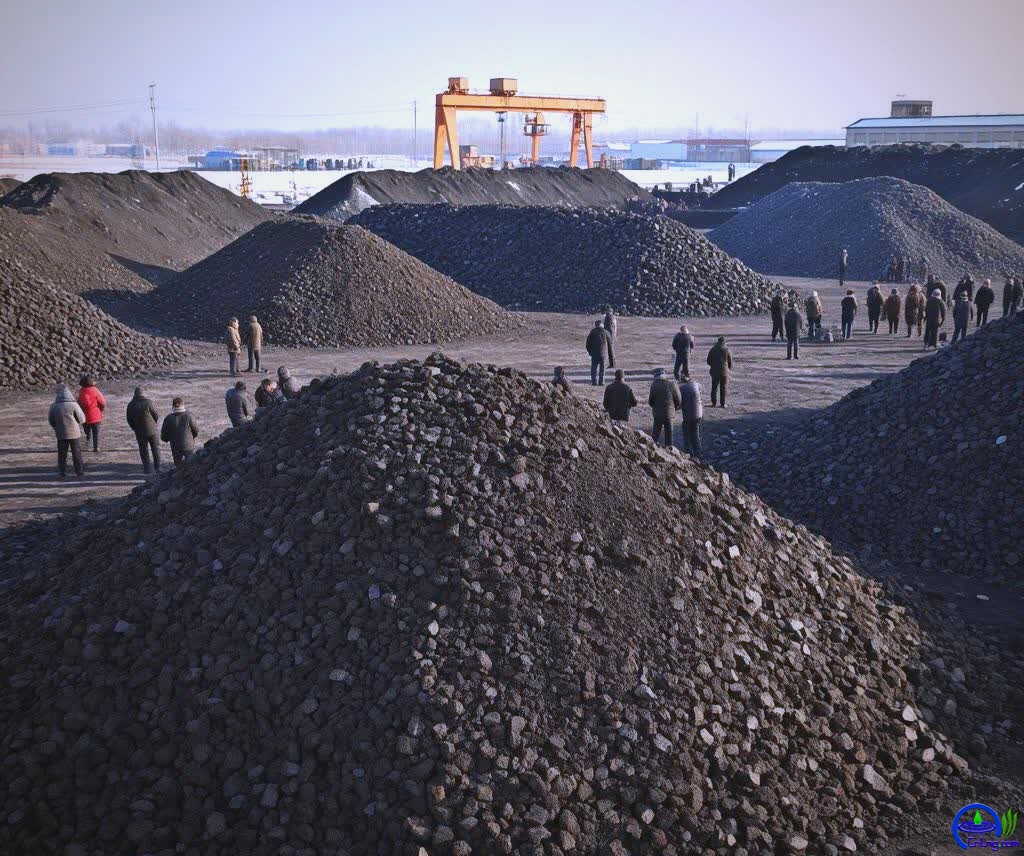
摘要:近期,国内煤炭市场快速走弱,整体行情跌至阶段性冰点,产地出货困难,市场悲观情绪蔓延。各主产区表现惨淡,降价促销成为普遍现象,而神华外购价、珠海华南电厂接货价格也纷纷遇冷,煤炭库存持续积压,终端采购意愿偏低,下游市场普遍预计煤价大跌50元/吨左右,即:港口煤价800-820元/吨的下跌预期,行业暂时进入买方主导的弱势行情。
|
近期,国内煤炭市场快速走弱,整体行情跌至阶段性冰点,产地出货困难,市场悲观情绪蔓延。各主产区表现惨淡,降价促销成为普遍现象,而神华外购价、珠海华南电厂接货价格也纷纷遇冷,煤炭库存持续积压,终端采购意愿偏低,下游市场普遍预计煤价大跌50元/吨左右,即:港口煤价800-820元/吨的下跌预期,行业暂时进入买方主导的弱势行情。 Recently, the domestic coal market has rapidly weakened, with the overall market price dropping to a temporary low point. It is difficult for producers to sell their products, and pessimistic sentiments have spread throughout the market. The performance of major production areas has been dismal, with price cuts and promotions becoming a common phenomenon. Meanwhile, the purchase prices of Shenhua and Zhuhai South China Power Plant have also cooled down. Coal inventories continue to pile up, and the purchasing intentions of end-users are low. The downstream market generally expects a coal price drop of around 50 yuan per ton, that is, an expected decline of 800 - 820 yuan per ton for the port coal price. The industry has temporarily entered a weak market dominated by buyers. 国际能源价格下行,成为本轮国内煤价走弱的重要外部推手。美国WTI原油价格重回战事爆发前的价格水平,形成连锁利空传导效应。原油价格大幅回落带动国际海运费大幅跳水,直接压低进口煤综合到岸成本。低价进口煤趁机大量涌入国内市场,对国产煤形成强烈冲击,进一步挤压国内北港煤的销售空间,让本就僵持的国内煤炭市场承压加重,内外联动的下跌逻辑清晰明确。 The decline in international energy prices has become an important external factor contributing to the weakening of domestic coal prices in this round. The price of WTI crude oil in the United States has returned to the level before the war broke out, creating a chain of negative effects. The significant drop in crude oil prices has led to a sharp decline in international shipping fees, directly lowering the comprehensive import coal landed costs. The large influx of low-priced imported coal into the domestic market has directly impacted domestic domestic coal, causing a strong shock to domestic coal production. This has further squeezed the sales space of domestic coal at the northern ports, adding more pressure to the already stagnant domestic coal market. The downward trend with internal and external linkage is clear and definite. 国内需求端全面疲软,是煤矿卖不动货的主要内因。电力行业方面,南方汛期降水充足,尚未出梅,水电出力大幅提升,叠加风电、光伏等新能源持续发力,大幅替代火电消耗,火电用煤需求明显收缩。同时,产地、港口、电厂各环节煤炭库存均处于高位,电厂依托长协煤稳定保供,完全以消耗自有库存为主,基本不主动采市场煤。非电行业方面,水泥、建材、化工等产业开工率不理想,企业利润承压,对高位货接受度极低,普遍按需刚需采购,无任何囤货备料行为。 The overall weakness in domestic demand is the main internal reason why coal mines cannot sell their goods. In terms of the power industry, there is sufficient rainfall during the flood season in the southern region, and the plum blossoms have not yet emerged. The output of hydropower has significantly increased, coupled with the continuous development of new energy such as wind power and photovoltaics, which have greatly replaced the consumption of thermal power. As a result, the demand for coal for thermal power has significantly shrunk. At the same time, coal inventories in various links such as production areas, ports, and power plants are at a high level. Power plants rely on long-term coal contracts to ensure stable supply and mainly consume their own inventory, without actively mining market coal. In terms of non electricity industries, the operating rates of industries such as cement, building materials, and chemicals are not ideal, putting pressure on corporate profits. The acceptance of high-end goods is extremely low, and there is generally on-demand procurement without any hoarding or material preparation behavior. 当前市场博弈加剧,贸易端恐慌情绪蔓延,煤价下行压力持续放大。目前, 市场定价权完全掌握在下游手中,采购方“买涨不买落”,普遍保持观望、拖延,静待煤价跌至谷底再采,倒逼卖家大幅降价促销。中间贸易商受发运倒挂影响,拿货意度谨慎,不再主动备货补库。同时部分前期高位囤货的贸易商为规避更大亏损,选择割肉抛售库存,进一步引发市场恐慌,加速煤价回落。整体来看,动力煤受长协托底,叠加用煤高峰到来影响,入夏前暴跌至800元/吨以下几无可能,但依然存在跌至800-820元/吨的合理回调空间的可能。 The current market competition is intensifying, and panic sentiments are spreading in the trade sector. The downward pressure on coal prices continues to increase. Currently, the pricing power of the market is completely in the hands of the downstream. Buyers "buy up rather than hold back", generally remain on the sidelines and delay their purchases, waiting for the coal price to reach its lowest point before making a purchase. This forces sellers to significantly reduce prices for promotion. Middle traders are affected by the shipping price gap and are cautious in their purchase intentions. They no longer actively stock up for replenishment. At the same time, some traders who had previously accumulated large stocks at high prices have chosen to sell their inventory to avoid greater losses, further triggering market panic and accelerating the fall in coal prices. Overall, due to the support of long-term contracts and the impact of the peak period of coal usage, it is almost impossible for thermal coal prices to drop below 800 yuan/ton before summer. However, there is still a possibility of a reasonable correction to the price range of 800-820 yuan/ton. |